Note
Go to the end to download the full example code.
Latvia battery financing: test the implied merchant trading contribution#
News (9 November 2026): Byhmgard reported a loan of just over EUR 3 million toward its approximately EUR 6.1 million, 14.99 MW / 30 MWh SW Power project in Riga. The issuer forecasts ~EUR 20 million in merchant arbitrage revenue over 2027-2047, with a separate potential EUR 33 million from balancing/capacity services. These are NOT realized proceeds.
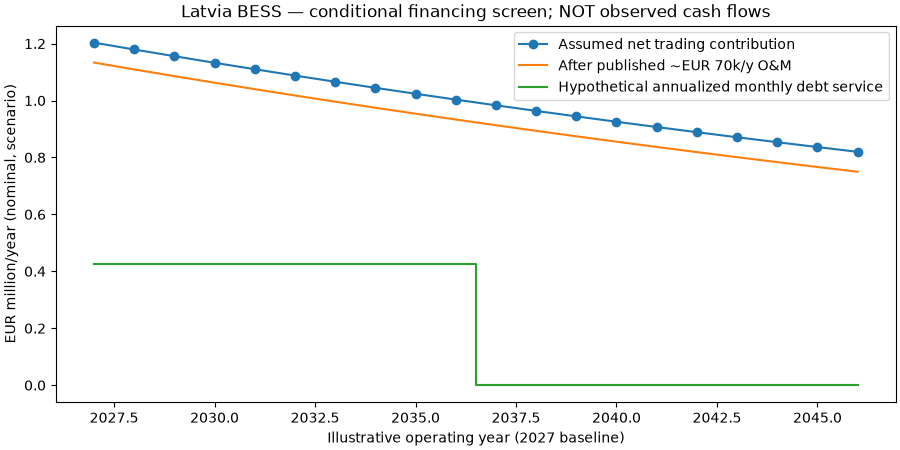
Decision: What captured net trading contribution would be required to reach EUR 20 million, and how would a hypothetical level loan compare with cash available for debt service?
Evidence: dated issuer-fact snapshot;
scientific screening guide.
The project company did not disclose actual loan interest, amortization,
realized spreads or measured battery dispatch. Modelled utilization, losses,
degradation, debt rate and tenure are ILLUSTRATIVE ASSUMPTIONS.
Important: The issuer uses the term revenue; this example computes net captured spread after electricity purchases. These are not necessarily the same accounting quantity. None of the plots validates the EUR 20 million forecast.
Load date-stamped evidence separately from scenario assumptions.
import json
from dataclasses import replace
from pathlib import Path

import matplotlib.pyplot as plt

from energy_methods.bess_merchant_finance import (
    BatteryFinanceScenario,
    BatteryTradingScenario,
    merchant_cashflow_screen,
    required_captured_margin_eur_per_mwh,
)

file_path = Path(globals().get("__file__", Path.cwd() / "plot_latvia_bess_finance.py"))
evidence = json.loads(
    (file_path.resolve().parent / "latvia_bess_finance_2026.json").read_text(encoding="utf-8")
)
facts = evidence["reported_facts"]
assumptions = evidence["illustrative_assumptions_not_reported"]
assert facts["project_loan_relation"] == "just over"

trading = BatteryTradingScenario(
    grid_charge_mwh_per_cycle=assumptions["charging_grid_mwh_per_full_cycle"],
    equivalent_cycles_per_day=assumptions["cycles_per_day"],
    round_trip_efficiency=assumptions["round_trip_efficiency"],
    availability=assumptions["availability"],
    annual_capacity_retention=assumptions["annual_capacity_retention"],
    captured_margin_eur_per_mwh=0.0,
)
finance = BatteryFinanceScenario(
    senior_debt_eur=assumptions["debt_assumed_eur"],
    annual_interest_rate=assumptions["interest_rate_assumed"],
    debt_tenor_years=assumptions["loan_tenor_assumed_years"],
    annual_fixed_opex_eur=facts["opex_approx_eur_per_year"],
)
years = assumptions["years"]
target = facts["arbitrage_revenue_forecast_approx_eur_2027_2047"]
margin = required_captured_margin_eur_per_mwh(target, trading, years)
scenario = replace(trading, captured_margin_eur_per_mwh=margin)
projection = merchant_cashflow_screen(scenario, finance, years)
print("SW Power: issuer-announced FACTS (not metered production):")
print(f"  Grid connection {facts['grid_connection_mw']} MW; storage ~30 MWh")
print(
    f"  Project-financing requirement ~EUR "
    f"{facts['total_financing_requirement_approx_eur'] / 1e6:.2f}m"
)
print(f"  Bank loan JUST OVER EUR {facts['project_loan_lower_bound_exclusive_eur'] / 1e6:.1f}m")
print(f"  Forecast arbitrage REVENUE ~EUR {target / 1e6:.0f}m/20y; NOT independently verified")
print("SCENARIO, not market observation: 30 MWh/cycle, one cycle/day, 88% RTE, ")
print("  95% availability, 2%/y assumed fade, assumed EUR 3.05m debt at 7%/10y")
print(f"  Conditional net captured margin required: EUR {margin:.2f}/delivered MWh")
print(f"  Assumed level annual debt payment: EUR {projection[0].debt_service_eur:,.0f}")
print("  Excludes charging-price revenue-definition uncertainty, tax, insurance,")
print("  second-half supplier credit, actual loan terms and financing covenants.")
SW Power: issuer-announced FACTS (not metered production):
  Grid connection 14.99 MW; storage ~30 MWh
  Project-financing requirement ~EUR 6.10m
  Bank loan JUST OVER EUR 3.0m
  Forecast arbitrage REVENUE ~EUR 20m/20y; NOT independently verified
SCENARIO, not market observation: 30 MWh/cycle, one cycle/day, 88% RTE,
  95% availability, 2%/y assumed fade, assumed EUR 3.05m debt at 7%/10y
  Conditional net captured margin required: EUR 131.46/delivered MWh
  Assumed level annual debt payment: EUR 424,957
  Excludes charging-price revenue-definition uncertainty, tax, insurance,
  second-half supplier credit, actual loan terms and financing covenants.
Illustrative annual cash contribution vs. level monthly loan payments.
fig, ax = plt.subplots(figsize=(9, 4.5), layout="constrained")
calendar_years = [2027 + cash.year_index for cash in projection]
ax.plot(
    calendar_years,
    [cash.contribution_eur / 1e6 for cash in projection],
    marker="o",
    label="Assumed net trading contribution",
)
ax.plot(
    calendar_years,
    [cash.cash_available_for_debt_eur / 1e6 for cash in projection],
    label="After published ~EUR 70k/y O&M",
)
ax.step(
    calendar_years,
    [cash.debt_service_eur / 1e6 for cash in projection],
    where="mid",
    label="Hypothetical annualized monthly debt service",
)
ax.set(
    xlabel="Illustrative operating year (2027 baseline)",
    ylabel="EUR million/year (nominal, scenario)",
    title="Latvia BESS — conditional financing screen; NOT observed cash flows",
)
ax.legend()
plt.show()
No bank pricing was published: rate sensitivity is explicitly hypothetical.
fig, ax = plt.subplots(figsize=(8.5, 4), layout="constrained")
rates = assumptions["interest_rate_sensitivity"]
lowest_covers = []
for rate in rates:
    cash = merchant_cashflow_screen(scenario, replace(finance, annual_interest_rate=rate), years)
    ratios = [row.cash_cover_ratio for row in cash if row.cash_cover_ratio is not None]
    lowest_covers.append(min(ratios))
ax.plot([100 * rate for rate in rates], lowest_covers, marker="o")
ax.axhline(1, color="black", linestyle=":", label="1.0x simple cash cover")
ax.set(
    xlabel="Assumed annual debt interest rate (%)",
    ylabel="Minimum projected cash / level debt payment (x)",
    title="Illustrative debt-cover sensitivity, NOT lender-calculated DSCR",
)
ax.legend()
plt.show()
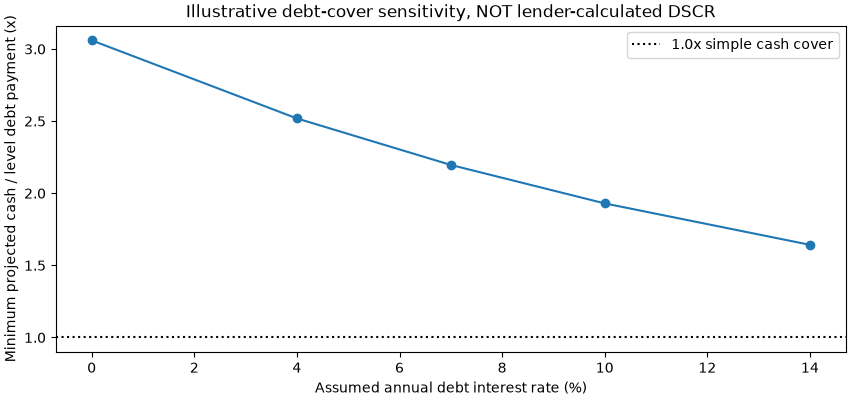
The target uses an issuer revenue FORECAST as a conditional net-margin goal. Obtain signed loan terms, Nord Pool Latvia price series, actual trading charges, dispatch constraints and degradation warranty before credit/investment decisions. Reproduce: uv run –no-sync python examples/analysis/plot_latvia_bess_finance.py
Total running time of the script: (0 minutes 0.172 seconds)